When a Crash Changes Everything: Understanding the Blueprint for Lifetime Care
Key Takeaways: A life care plan is a detailed, medically grounded projection of every treatment, device, medication, and support service a catastrophically injured person may need for life, along with the cost of each item, making it a common foundation of future damages in a San Antonio catastrophic crash claim. Certified life care planners build these documents alongside treating physicians, economists, and vocational experts, and their credibility can influence how well the projection withstands insurer attacks. Texas law generally treats projected future care as economic damages, defined in Chapter 41 of the Civil Practice and Remedies Code, while § 18.001 affidavits may help establish that charges were reasonable and necessary but are not evidence of causation. Proportionate responsibility under § 33.001 can reduce or bar recovery, giving insurers incentive to shift blame onto the injured person. Even a well-documented plan is limited by available coverage, so identifying potential UM/UIM, commercial, employer, and third-party sources is important. Because Texas generally allows only two years to file, subject to limited exceptions, and building a credible plan can take months, early legal action matters.
A life care plan is a detailed, medically grounded document projecting the services, treatments, devices, medications, and supports a catastrophically injured person may need for life, along with the projected cost of each item. In a San Antonio catastrophic crash claim, it often becomes the backbone of the future damages calculation. When a spinal cord injury leaves someone paraplegic, a traumatic brain injury steals their ability to work, or a limb is lost in a high-speed collision on Loop 410, the medical bills already incurred may represent only a fraction of the true loss. A life care plan seeks to put a defensible number on the decades that follow, though a jury ultimately decides what future care is reasonably probable and what it will cost.
If your family is facing a lifetime of care after a devastating collision, Wyatt Law Firm is ready to stand with you. Paula Wyatt has spent decades confronting corporate defendants and insurance carriers who try to reduce a human life to a lowball number. Call 210-340-5550 or contact our team today to discuss your situation.
What a Life Care Plan Actually Contains
A life care plan is far more than a list of doctor visits. It’s a comprehensive medical cost projection built from the injured person’s diagnoses, prognosis, functional limitations, and treating physicians’ recommendations, often spanning decades and accounting for changing needs over time.
A thorough plan generally addresses:
- Future surgeries, hospitalizations, and physician follow-up care
- Prescription medications and durable medical equipment, including wheelchairs, prosthetics, and ventilators
- Attendant care, skilled nursing, or residential placement
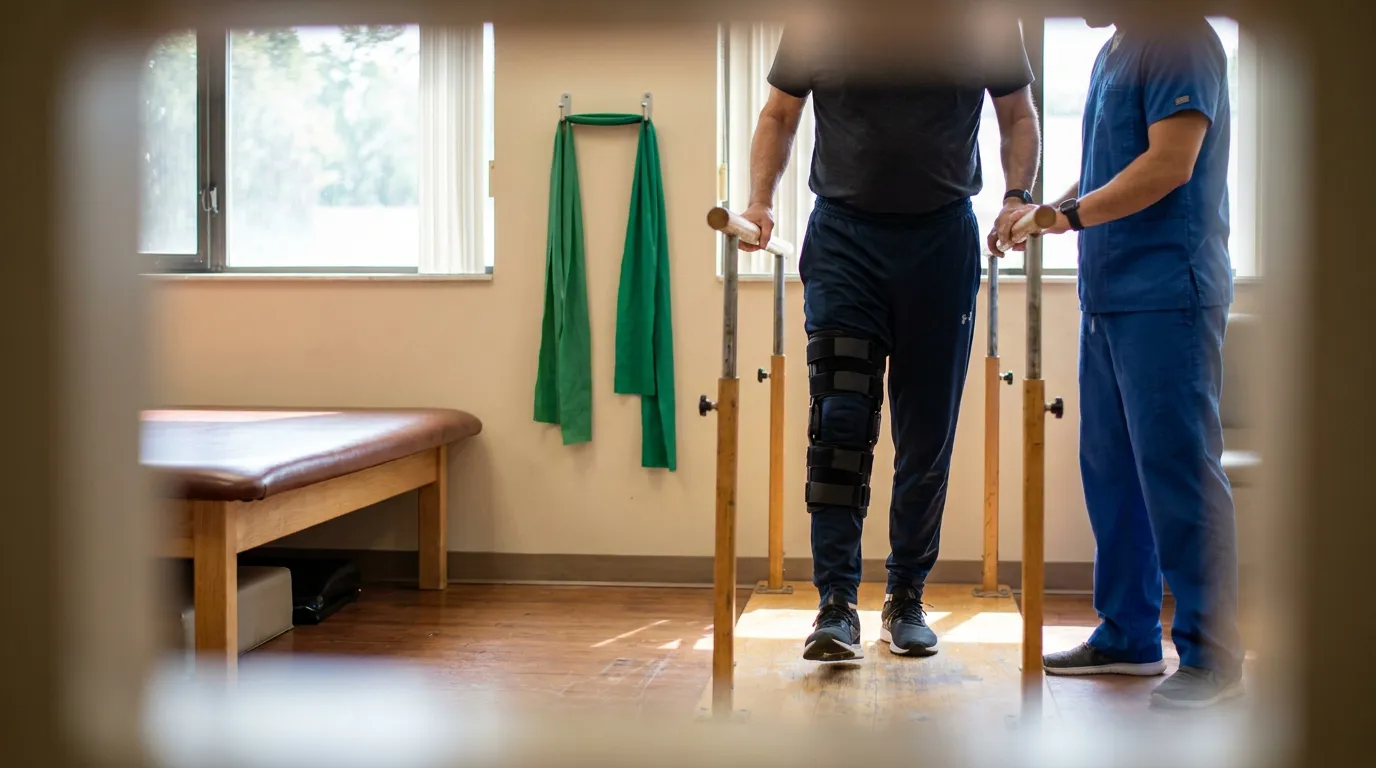
- Physical, occupational, speech, and cognitive rehabilitation therapy
- Home and vehicle modifications for accessibility
- Diagnostic testing and complication management, such as pressure sore or infection treatment
- Case management and vocational support services
Each line item is generally tied to a frequency, duration, and cost figure drawn from regional pricing data, helping a jury understand not just that care may be expensive, but why. Whether any category is recoverable depends on the evidence supporting it and the court’s rulings on admissibility.
Who Prepares the Plan and Why Their Credentials Matter
A certified life care planner, often a rehabilitation nurse or counselor with advanced training, typically prepares the document. This expert reviews medical records, interviews the injured person and family, consults treating physicians, and applies published standards of practice. The planner’s credibility matters enormously, because opposing carriers often retain their own consultants to argue the projected care is excessive or unrelated to the crash, and a planner’s qualifications and methodology may be challenged before testimony reaches a jury.
Life care planners rarely work alone. An economist may convert cost figures into present value, accounting for medical inflation and life expectancy. Physicians provide the medical foundation for each recommendation, since a non-physician planner generally cannot supply underlying medical opinions. Vocational specialists assess lost earning capacity. A claim’s strength often depends on how tightly these professionals’ opinions fit together.
The Role of Treating Physicians
Treating doctors help anchor the plan in reality. A planner’s projections carry more weight when the treating neurosurgeon, physiatrist, or trauma surgeon has documented the same needs in the medical record. Defense teams often look hard for gaps between what the plan recommends and what the doctors actually said.
Why Timing of the Plan Matters
Preparing a plan too early can undervalue a claim. Catastrophic injuries often require months or years before physicians can state a reliable long-term prognosis. Waiting until the injured person reaches maximum medical improvement may produce a more accurate, defensible projection, though limitations periods and expert disclosure deadlines can constrain that timeline.
How Texas Law Treats Future Medical Costs in a Life Care Plan Catastrophic Injury Claim
Texas generally categorizes projected future care as economic damages. Chapter 41 of the Civil Practice and Remedies Code, which primarily governs exemplary damages, includes definitions in § 41.001 distinguishing economic from noneconomic and exemplary damages. This distinction matters because statutory caps and heightened proof standards for punitive awards don’t apply the same way to documented compensatory losses like future medical care. Recovery still requires proof, in reasonable probability, that care will be needed and of its reasonable cost.
Certain commercial vehicle cases carry their own statutory framework. Under § 72.051, a "civil action" includes claims for bodily injury or death caused in a collision involving a commercial motor vehicle, and the statute ties "compensatory damages" and "exemplary damages" to the § 41.001 definitions. Chapter 72 also allows a defendant to request a bifurcated trial in qualifying cases. If an eighteen-wheeler or delivery truck caused your family’s loss, these provisions on commercial vehicle collision claims may shape how the case proceeds.
Proving charges are reasonable and necessary is a separate step. Tex. Civ. Prac. & Rem. Code § 18.001(b) provides that an affidavit stating a charge was reasonable and the service necessary may be sufficient evidence to support that finding, if served properly and not controverted by a timely counteraffidavit. Such an affidavit is not evidence of causation, and it addresses past charges rather than projected future care. Establishing that the crash caused the need for lifelong care generally requires separate medical testimony, and injured people who understand how catastrophic injury damages are recovered may be better positioned to protect their claims.
💡 Pro Tip: Keep a dated log of every medical appointment, every hour a family member spends providing care, and every out-of-pocket expense. Life care planners rely heavily on this documentation, and gaps can give insurers an opening to argue the care was never truly needed.
Fault Allocation Can Reduce Even a Well-Documented Plan
Texas applies a modified comparative fault rule, proportionate responsibility, that can reduce or eliminate recovery. Under § 33.001, a claimant generally cannot recover if their percentage of responsibility exceeds fifty percent. If a jury assigns the injured person fifty percent or less, the award, including the life care plan figure, is generally reduced proportionately.
This is one reason insurers often invest heavily in blaming the victim. The proportionate responsibility standard can give defense teams financial incentive to argue that a speeding, distracted, or improperly seated plaintiff contributed to their own outcome. When a life care plan projects millions in costs, even a modest shift in fault percentage can mean a large dollar swing, worth fighting for with accident reconstruction, black box data, and scene investigation.
Finding the Money to Fund Decades of Care
A life care plan may be only as valuable as the insurance and assets available to satisfy it. Texas requires only modest minimum liability limits, so a catastrophically injured person may discover the at-fault driver’s policy covers a small fraction of the projected need, one of the harshest realities families face.
| Potential Funding Source | What It May Cover |
|---|---|
| At-fault driver’s liability policy | Damages up to the policy limit |
| UM/UIM coverage on the victim’s own policy | Shortfall when the at-fault driver is uninsured or underinsured |
| Commercial or trucking policies | Substantially higher limits in commercial vehicle collisions |
| Employer or vicarious liability claims | Damages where the driver acted in the course of employment |
| Third-party defendants | Claims against vehicle, road design, or maintenance parties |
Uninsured and underinsured motorist coverage may help fill the gap. Chapter 1952 of the Texas Insurance Code addresses UM/UIM coverage, which insurers generally must offer unless the insured rejects it in writing. Families pursuing large life care plan awards frequently rely on this coverage when the at-fault party is uninsured or underinsured, though Texas law generally requires establishing the other driver’s liability and damages amount before benefits become payable. A skilled life care plan catastrophic injury claim lawyer can work to identify available coverage layers rather than accepting the first policy limit offered.
The Deadline That Can End the Claim Before It Begins
Texas generally requires personal injury lawsuits to be filed within two years of accrual, under § 16.003. If that deadline passes, the claim is generally subject to dismissal regardless of injury severity or how compelling the life care plan may be.
Limited exceptions may exist, but Texas courts often interpret them narrowly. Tolling doctrines and the discovery rule may apply in certain circumstances, such as claims on behalf of minors or injuries that couldn’t reasonably have been discovered, but they depend on specific facts. Claims against governmental entities involve separate notice requirements under the Texas Tort Claims Act, distinct from the civil limitations period and sometimes as short as six months or less under a local charter or ordinance. Because building a credible life care plan can take months, waiting to consult counsel can leave too little runway.
Frequently Asked Questions
1. How much does a life care plan increase a claim’s value?
There’s no fixed answer, it depends on the injury, age, life expectancy, and care required. In severe spinal cord or brain injury cases, projected future care may exceed all past medical bills combined. Outcomes always depend on specific facts and available coverage.
2. Will the insurance company accept the life care plan?
Often not without a fight. Carriers commonly retain their own consultants to challenge the frequency, duration, or necessity of projected care, arguing pre-existing conditions rather than the crash created the need. A well-supported plan grounded in treating physician recommendations may be harder to attack.
3. Can a life care plan be updated after it is prepared?
Often, yes. If a condition changes materially, complications develop, or litigation extends, the planner may revise projections. Updated opinions generally must be disclosed under the Texas Rules of Civil Procedure and any scheduling order, or their use at trial may be limited.
4. Does a life care plan cover non-medical needs?
It can. Depending on the injury, plans may include home modifications, adaptive vehicles, attendant care, and vocational services, still treated as economic damages when properly supported by evidence of medical necessity and reasonable cost.
5. Who pays for care while the case is pending?
This varies. Health insurance, letters of protection, Medicare, or Medicaid may cover treatment during litigation, and liens or subrogation interests often must be resolved from any recovery. An attorney can help evaluate how these obligations may affect a final result.
Your Family’s Future Deserves a Number Backed by Evidence
A catastrophic crash doesn’t end when the ambulance leaves. It can continue through surgeries, therapy, home health aides, and a lifetime of adaptation, and Texas law may permit recovery of those future costs when proven with credible evidence. A life care plan seeks to translate that lifetime of need into a documented, defensible figure a jury can understand. Building one generally requires coordination among physicians, planners, and economists, and defending it may require a lawyer who has taken these cases to trial before.
Insurance companies have entire departments dedicated to shrinking your family’s future. Wyatt Law Firm has spent decades on the other side of that fight, standing with the injured and the grieving across San Antonio and South Texas. Reach out at 210-340-5550 or request a free consultation to learn how a properly built life care plan may help protect what comes next.
Disclaimer: This content is for informational purposes only and is not legal advice. Every case is unique, and results may vary. Consult an attorney about your specific circumstances.